
Updated on 26 October 2026.
When an employee works temporarily in another town in Romania or abroad, the employer covers travel and accommodation and pays an allowance, commonly called per diem. Below are the Labour Code rules, the difference between what a private company can pay and what a public-sector employee receives, the ceiling up to which the per diem is tax-free, and the documents required.
Delegation and secondment
The employer may unilaterally change the place of work by delegating or seconding the employee. During that time, the employee keeps their position and all rights under the contract (art. 42 of the Labour Code, Law no. 53/2003).
- Delegation means temporarily carrying out work tasks outside the usual place of work, on the employer’s instructions (art. 43). It may last up to 60 calendar days in 12 months and can be extended by periods of up to 60 days only with the employee’s consent (art. 44 para. (1)).
- Secondment means a temporary change of workplace to another employer, in that employer’s interest (art. 45). It may last up to one year, with exceptional extensions every 6 months, with the consent of both parties (art. 46 paras. (1) and (2)).
A delegated or seconded employee is entitled to travel and accommodation costs and to a delegation or secondment allowance, under the law or the applicable collective agreement (art. 44 para. (2) and art. 46 para. (4)).
What a private company can pay and what a public employee gets
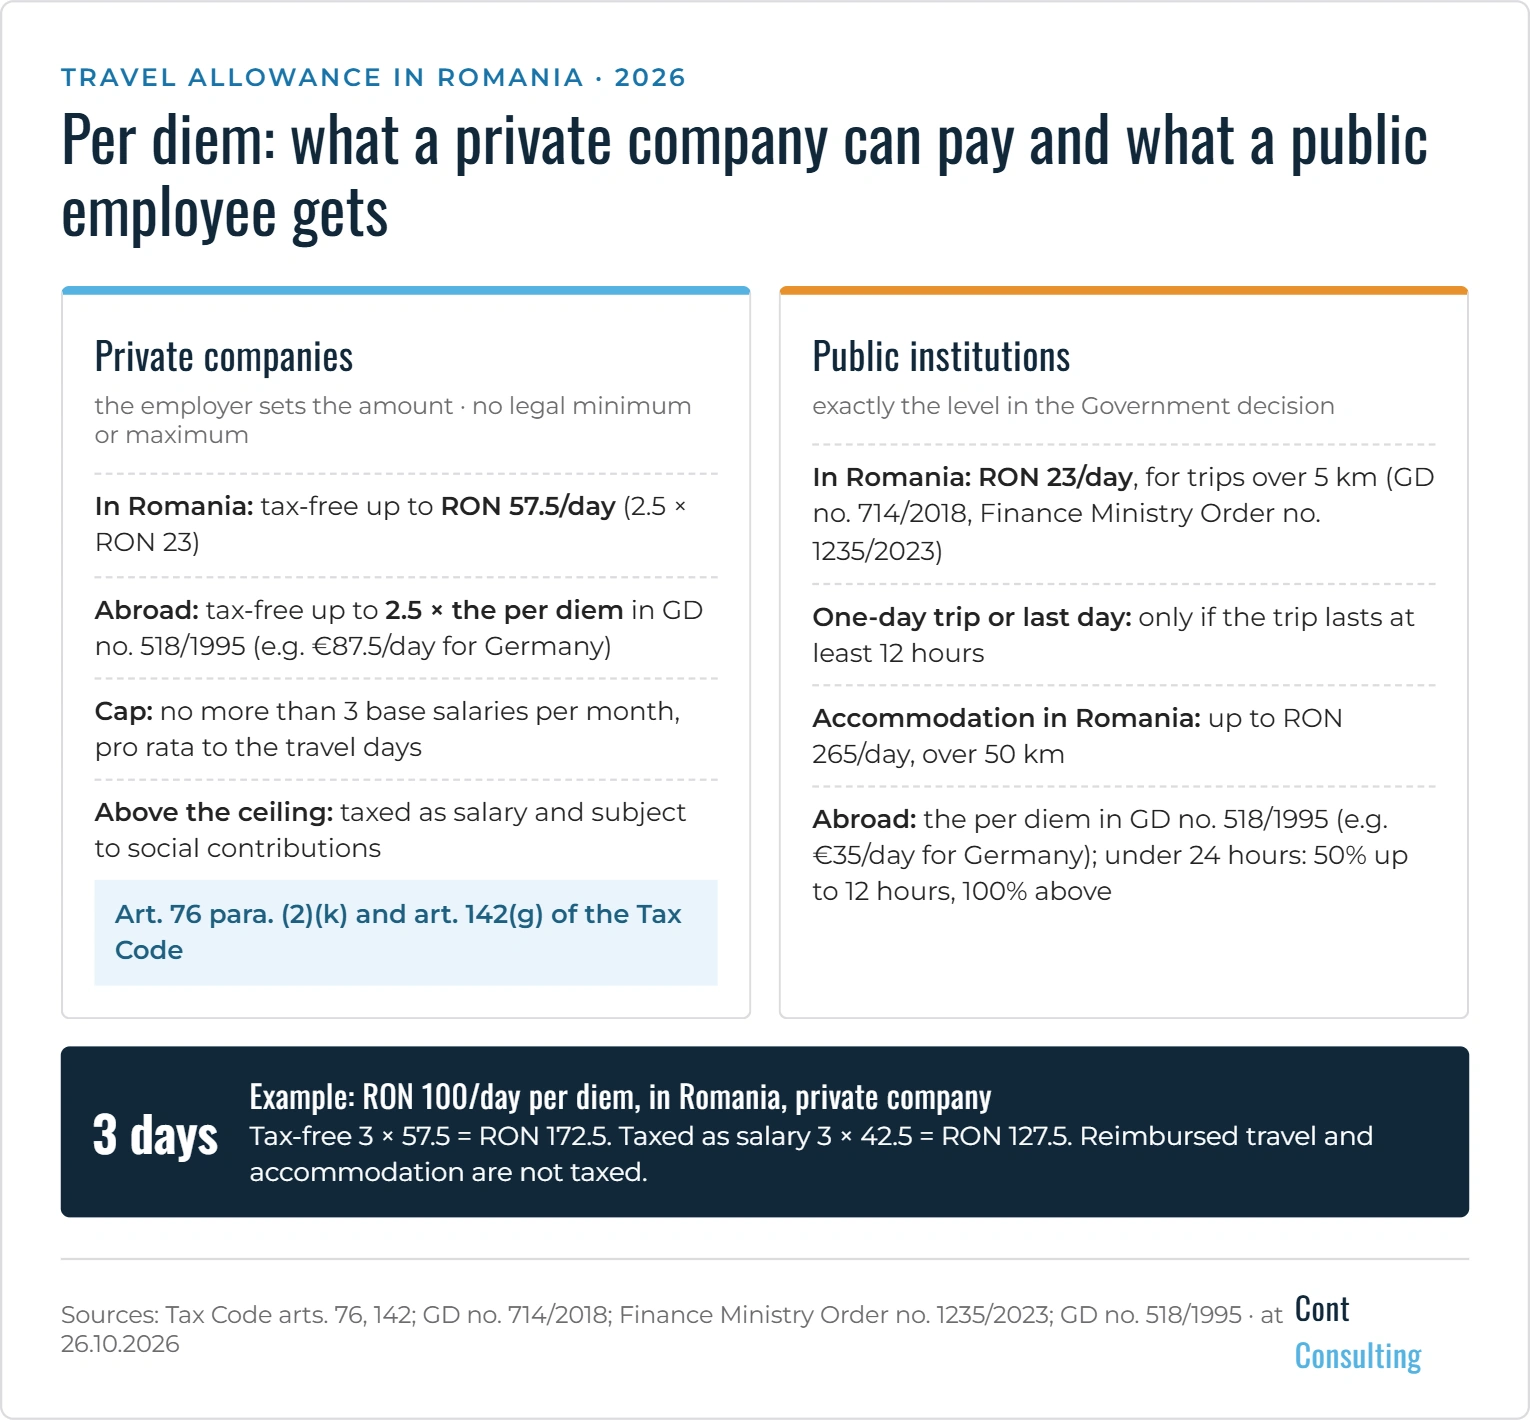
Private companies set the per diem themselves, through the collective agreement, internal rules, the employment contract or an employer’s decision. The law sets neither a minimum nor a maximum, so any amount can be paid. The difference lies in taxation: up to a ceiling the per diem is tax-free, and anything above it is taxed as salary.
Public institutions pay exactly the level set by Government decision, no more and no less.
| Private companies | Public institutions | |
|---|---|---|
| Who sets the amount | the employer (collective agreement, internal rules, contract or decision) | the Government: GD no. 714/2018 (in Romania) and GD no. 518/1995 (abroad) |
| Legal minimum | none | – |
| Legal maximum | none | the level in the decision |
| In Romania | any amount; tax-free up to RON 57.5 per day (2.5 × RON 23) | RON 23 per day (Finance Ministry Order no. 1235/2023), for trips over 5 km |
| Conditions in Romania | as set by the employer | for a one-day trip and for the last day, the allowance is paid only for at least 12 hours (annex to GD no. 714/2018, art. 1 para. (5)) |
| Accommodation in Romania | based on receipts, with no tax ceiling | accommodation allowance of up to RON 265 per day, over 50 km (Finance Ministry Order no. 1235/2023) |
| Abroad | any amount; tax-free up to 2.5 × the per diem in GD no. 518/1995, e.g. EUR 87.5 per day for Germany | the per diem in the annex to GD no. 518/1995, e.g. EUR 35 per day for Germany, France or Italy |
| Partial days abroad | rule set by the company | 50% up to 12 hours, 100% above 12 hours (art. 7^1 para. (2) of GD no. 518/1995) |
| Cap of 3 base salaries | applies to the tax-free ceiling | – |
The public-sector levels matter for private companies too, because the tax-free ceiling is calculated from them.
The tax-free ceiling
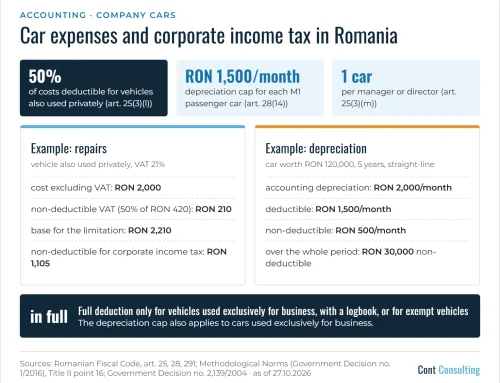
The per diem, including the allowance specific to transnational posting and the additional payments to mobile road transport workers, is not taxed up to a ceiling (art. 76 para. (2) letter k) of the Tax Code):
- in Romania: 2.5 × RON 23 = RON 57.5 per day;
- abroad: 2.5 × the per diem set for that country, e.g. 2.5 × EUR 35 = EUR 87.5 per day for Germany;
- in both cases, no more than 3 base salaries for the position. The cap is calculated separately for each month: the 3 salaries are divided by the number of working days in the month, and the result is multiplied by the number of travel days in that month.
The part above the ceiling is taxed as employment income and included in the social contribution base (art. 76 para. (2) letter k) and art. 142 letter g) of the Tax Code). Amounts for travel and accommodation are not counted: they are neither taxed nor subject to contributions (art. 142 letter g)).
Example. An employee with a base salary of RON 5,000 is sent for 3 days to another town, in a month with 21 working days. The company pays a per diem of RON 100 per day. The tax-free ceiling is RON 57.5 per day. The 3-salary cap is 15,000 / 21 × 3 = RON 2,142.86, so it does not apply. Tax-free: 3 × 57.5 = RON 172.5. Taxed as salary: 3 × 42.5 = RON 127.5.
Directors and managers under a mandate contract
For directors, managers under a mandate contract and managers under a management contract, the same 2.5 ceiling applies, capped at 3 monthly remunerations under the contract (art. 76 para. (2) letter m)). For them, the daily ceiling applies only if the trip lasts more than 12 hours, each 24 hours counting as one travel day (art. 142 letter i)).
Documents required
- The travel order (delegation), form code 14-5-4 in Order of the Minister of Public Finance no. 2634/2015. It serves as the travel instruction, the expense settlement document and the supporting document in the accounts. It shows the employee’s name and position, the purpose and place of the trip, and the date and time of departure and return. Download our travel order template (Word, in Romanian).
- The expense report, with supporting documents (invoices, receipts) issued in the company’s name, not the employee’s.
- The internal decision or rules setting the per diem. The law does not expressly require it, but we recommend it, as it supports the amounts in a tax or labour inspection.
Cash payments of travel expenses (transport, per diem, accommodation and unforeseen costs) are exempt from the cash limits of Law no. 70/2015, within the amounts due (art. 5 letter b)). See Law no. 70/2015 and the limits on cash transactions in Romania.
We can help with per diem calculations and documents: see Payroll and HR services.
Note: This text is valid on the date of the update, is for information only and reflects the interpretation of Cont Consulting’s specialists. It does not replace the legal provisions in force.
Sources: Romanian Tax Code (Law no. 227/2015), arts. 76 and 142; Labour Code (Law no. 53/2003), arts. 42–47; GD no. 714/2018 and Finance Ministry Order no. 1235/2023; GD no. 518/1995 as amended by GD no. 582/2015; Law no. 70/2015, art. 5; Order no. 2634/2015. Consolidated versions checked on 26.10.2026.