
Updated on 26 October 2026.
The reinvested profit tax exemption is one of the most generous incentives in the Romanian Tax Code, and it is used fairly rarely. For companies upgrading their equipment without grant funding, it can be a significant source of financing: the profit tax on the amount invested stays in the company. The rules are in art. 22 of the Tax Code (Law no. 227/2015).
Who can apply the exemption
The exemption is part of Title II of the Tax Code, on profit tax. It therefore applies only to companies paying profit tax. Micro-enterprises, taxed on revenue under Title III, cannot apply it. Companies that move from micro-enterprise tax to profit tax during the year can apply the exemption for assets put into use from the quarter in which they became liable to profit tax, based on the cumulative gross accounting profit from the start of that quarter (art. 22 para. (4)). The conditions for moving to profit tax are explained in our article on micro-enterprise income tax in Romania in 2026.
Which assets qualify
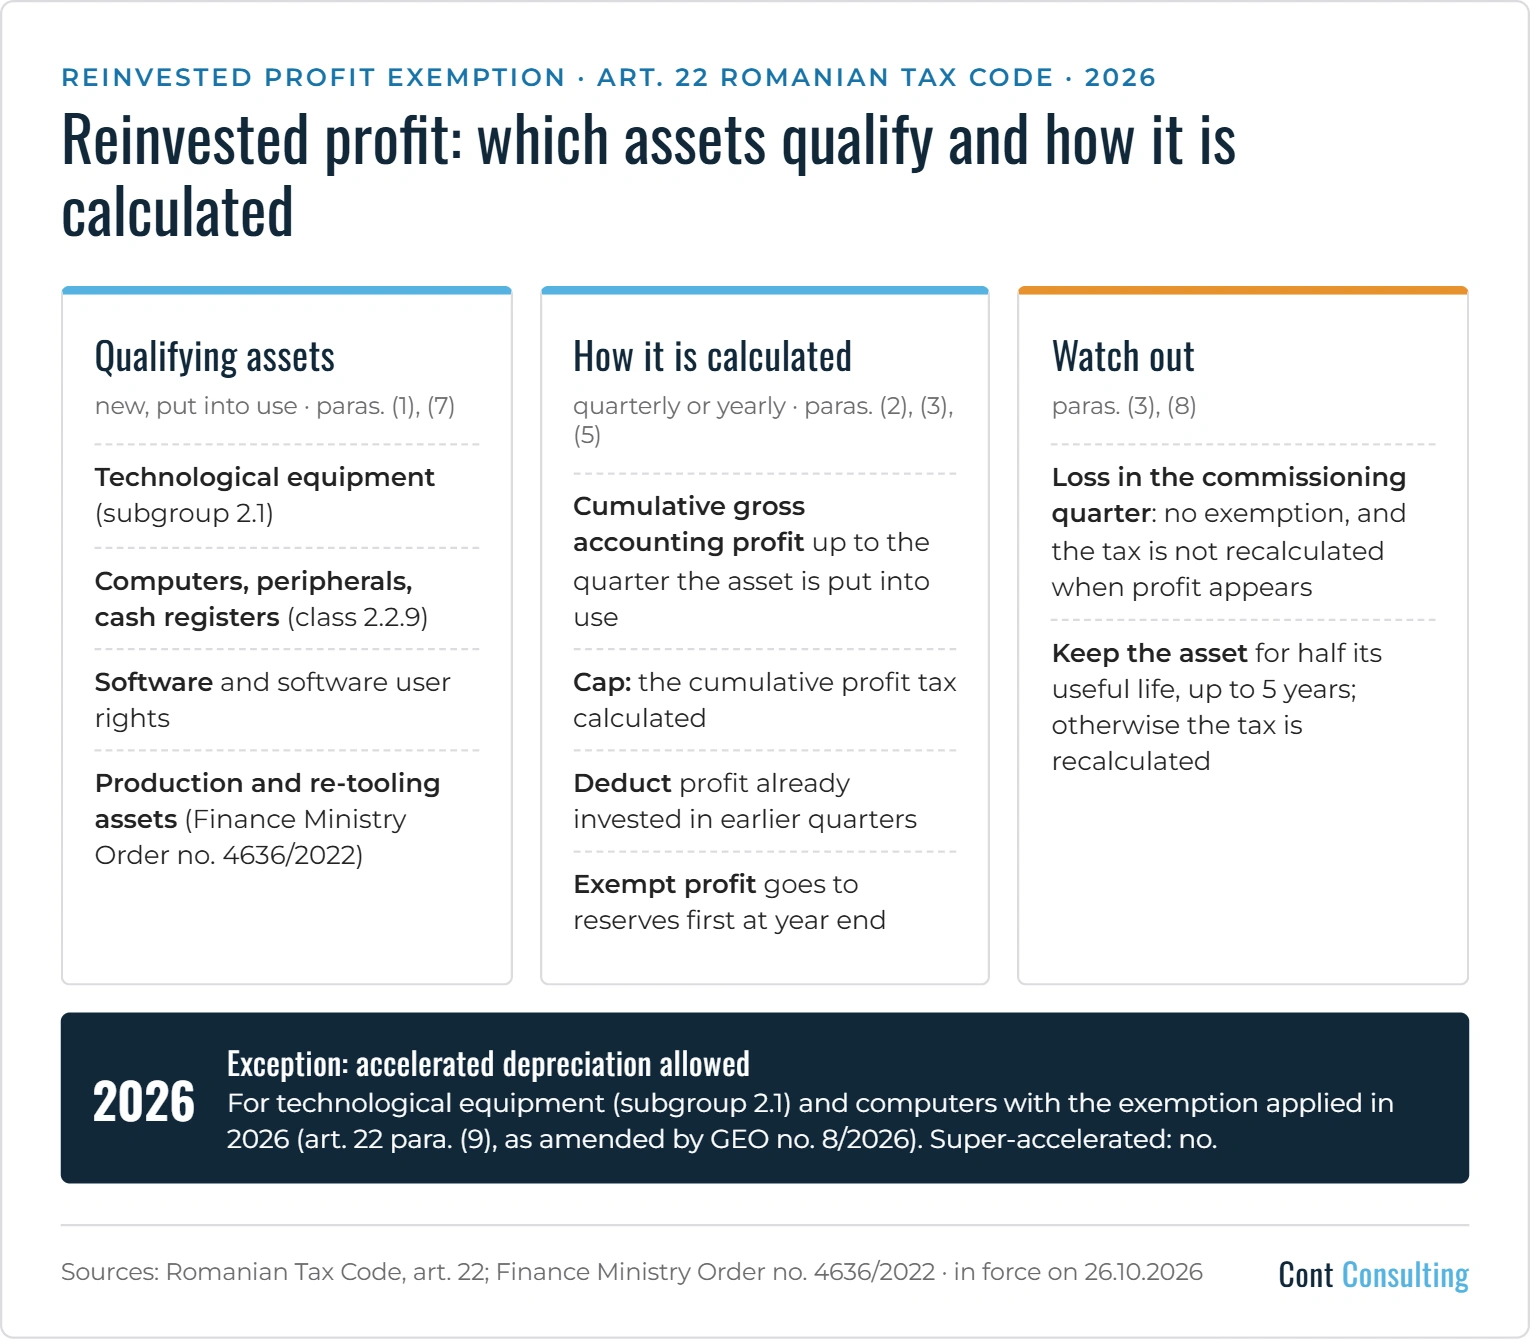
The profit must be invested in assets produced or acquired, including under finance leases, put into use and used in the business (art. 22 para. (1)):
- technological equipment, i.e. machinery, tools and working installations (subgroup 2.1 of the Catalogue on the classification and normal useful lives of fixed assets);
- computers and peripheral equipment, cash registers, control and invoicing machines (class 2.2.9 of the Catalogue);
- software and software user rights;
- assets used in production and processing and assets representing re-tooling, set by Finance Ministry Order no. 4636/2022: industrial buildings, production and assembly halls, agricultural buildings and storage, silos, greenhouses and polytunnels, measurement, control and regulation equipment (subgroup 2.2), animals and plantations (subgroup 2.4) and the other classes listed in the order.
The assets must be new, as defined in the methodological norms (art. 22 para. (7)). Profit invested in supporting dual vocational education is also exempt (art. 22 para. (1^1)).
How it is calculated
- The invested profit is the cumulative gross accounting profit from the start of the year up to the quarter or year in which the asset is put into use (art. 22 para. (2)).
- The exemption is capped at the profit tax calculated cumulatively from the start of the year up to the quarter of commissioning, for companies filing quarterly. For companies on the annual system, the cap is the tax calculated for the whole year of commissioning (art. 22 para. (2)).
- Investments in earlier quarters are deducted. If the company has already applied the exemption in the same year, the profit already used is deducted from the cumulative accounting profit (art. 22 para. (3)).
- The exemption is calculated quarterly or annually, depending on the company’s payment system (art. 22 para. (5)).
- Multi-year investments qualify for the parts put into use each year, based on partial works statements (art. 22 para. (6)).
Example. A company filing quarterly has, at 30 June, a cumulative gross accounting profit of RON 200,000. For simplicity, we assume taxable profit equals accounting profit, so the cumulative profit tax calculated is RON 32,000 (16% rate, art. 17). In Q2 it puts into use a new machine worth RON 150,000. The invested profit is RON 150,000, and the exemption is 150,000 × 16% = RON 24,000, below the RON 32,000 cap. The cumulative profit tax for the first half-year becomes RON 8,000.
What happens in case of a loss
If the company records an accounting loss in the quarter the asset is put into use, and a profit in the following quarter or at year end, the profit tax on the invested profit is not recalculated (art. 22 para. (3)). In practice, the exemption for that asset is lost. We analysed this situation in Reinvested profit tax exemption in Romania when the commissioning quarter ends with a loss.
If the company ends the year with an accounting loss, the tax on the invested profit is not recalculated and the amount is not allocated to reserves (art. 22 para. (5)).
Reserves
The profit for which the exemption was applied, less the part relating to the legal reserve, is allocated at the end of the financial year or during the following year, primarily to reserves, up to the accounting profit at the end of the financial year (art. 22 para. (5)).
How long the asset must be kept
The asset must be kept for at least half of its economic useful life, but no more than 5 years. Otherwise, the tax is recalculated, interest and late-payment penalties are due from the date the incentive was applied, and an amended return must be filed (art. 22 para. (8)). There is no recalculation if the asset is transferred in a reorganisation, sold in liquidation or insolvency, destroyed, lost, stolen or defective and replaced, or removed from the company’s assets to meet a legal obligation (art. 22 para. (8) letters a)–d)).
Depreciation: the 2026 exception
As a general rule, accelerated or super-accelerated depreciation cannot be chosen for assets benefiting from the exemption (art. 22 para. (9)). By way of exception, if the exemption is applied in 2026 to technological equipment (subgroup 2.1) or to computers and peripheral equipment, the company may opt for accelerated depreciation under art. 28 para. (5) letter b). The exception was introduced by Government Emergency Ordinance no. 8/2026 and applies from the 2026 tax year. For companies with a modified tax year, it applies to the modified tax year starting in 2026.
Note: This text is valid on the date of the update, is for information only and reflects the interpretation of Cont Consulting’s specialists. It does not replace the legal provisions in force.
Sources: Romanian Tax Code (Law no. 227/2015), arts. 17 and 22, consolidated version on legislatie.just.ro, checked on 26.10.2026; Finance Ministry Order no. 4636/2022.