
Updated on 27 October 2026.
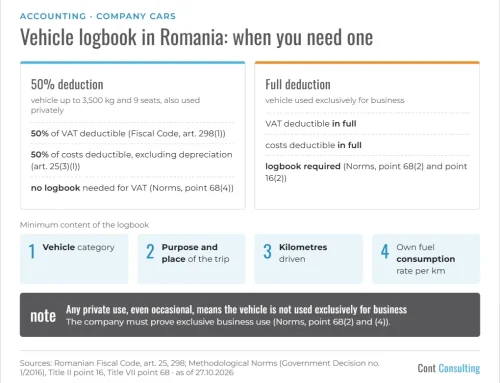
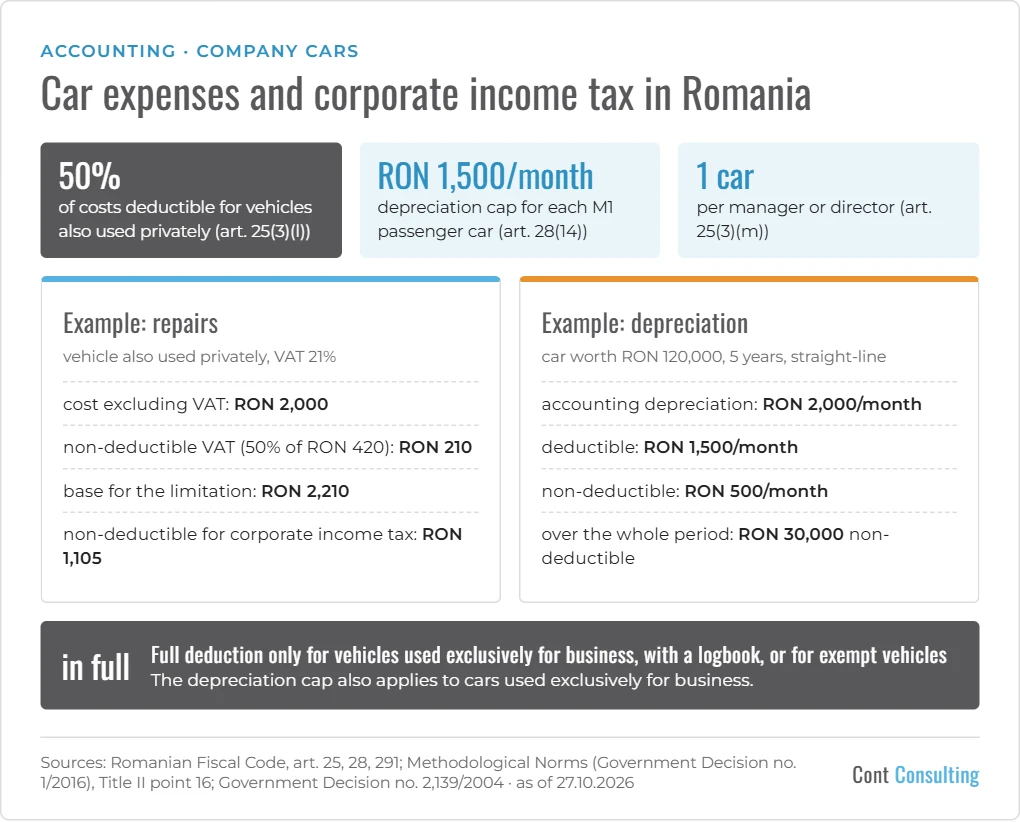
In Romania, companies paying corporate income tax can deduct only 50% of the costs of vehicles of up to 3,500 kg and up to 9 seats, including the driver’s seat, that are not used exclusively for business (Fiscal Code, art. 25(3)(l)). Depreciation is not included in this limit, but passenger cars have their own depreciation cap.
Which costs fall under the 50% limit
Costs directly attributable to the vehicle (Methodological Norms, point 16(3) and point 68(1)):
- fuel, lubricants, repairs, maintenance, spare parts;
- local vehicle tax, compulsory motor insurance (RCA), roadworthiness tests (ITP), the road toll (rovinietă);
- rent, interest, fees;
- non-deductible VAT;
- exchange differences from contracts other than leasing. For leasing, the 50% limit applies to the net unfavourable difference between foreign exchange income and expenses (art. 25(3)(l)).
The 50% limit for corporate income tax is applied after the VAT limitation, so it also applies to the non-deductible VAT (Norms, point 16(3)).
Worked examples (VAT 21%)
Repairs of RON 2,000
| Item | Amount |
|---|---|
| Cost excluding VAT | RON 2,000 |
| VAT (21%) | RON 420, of which 50% is deductible: RON 210 |
| Non-deductible VAT, recorded as an expense | RON 210 |
| Base for the 50% limitation | RON 2,210 |
| Non-deductible for corporate income tax | RON 1,105 |
Fuel of RON 1,000
| Item | Amount |
|---|---|
| Cost excluding VAT | RON 1,000 |
| VAT (21%) | RON 210, of which 50% is deductible: RON 105 |
| Non-deductible VAT, recorded as an expense | RON 105 |
| Base for the 50% limitation | RON 1,105 |
| Non-deductible for corporate income tax | RON 552.50 |
Depreciation: the RON 1,500 monthly cap
For M1 passenger cars (up to 9 seats, including the driver’s seat), depreciation is deductible up to RON 1,500 per month for each car (art. 28(14)). The cap also applies to cars used exclusively for business; the only exceptions are listed below.
Example. A car used exclusively for business, with VAT deducted in full, is recorded at RON 120,000. The useful life chosen is 5 years (Catalogue approved by Government Decision no. 2,139/2004, code 2.3.2.1.1 “Passenger cars”: 4–6 years), with straight-line depreciation.
| Item | Amount |
|---|---|
| Monthly depreciation (RON 120,000 / 60 months) | RON 2,000 |
| Deductible (cap) | RON 1,500 |
| Non-deductible per month | RON 500 |
| Non-deductible per year | RON 6,000 |
| Non-deductible over the whole period (5 years) | RON 30,000 |
The cap does not apply to vehicles used exclusively for emergency, security and courier services, vehicles used by sales and purchasing agents (including for test drives and demonstrations), paid passenger transport, and paid services, including rental and operating leases (art. 28(14)(a)–(d)).
Vehicles whose costs are fully deductible
Vehicles used exclusively for business, with a logbook (Norms, point 16(2)), and, regardless of use, vehicles used for emergency, security and courier services; by sales and purchasing agents; for paid passenger transport; for paid services, including rental to other persons and driving schools; and vehicles held as goods for sale (art. 25(3)(l) points 1–5).
For details on the logbook and a free template, see our article Vehicle logbook (foaie de parcurs) in Romania: when it is required and what it must contain.
Managers and directors
For persons in management and administration roles, the costs are deductible, within the limits above, for one passenger car per person (art. 25(3)(m)).
Micro-enterprises and sole traders (PFA)
Micro-enterprises do not pay corporate income tax, so these limits do not apply to them; the VAT rule applies if they are VAT-registered (art. 298). Sole traders (PFA) taxed on actual income are subject to the same 50% limitation (art. 68(7)(k)).
Our recommendations
- Decide for each vehicle whether it is used exclusively for business or whether you apply the 50% limitation.
- Keep a separate record of costs for each vehicle so that you can apply the limits.
- Check car depreciation against the RON 1,500 cap every month.
We can help you record car costs correctly: see our accounting services.
Note: This text is valid on the date of its update, is for information only and reflects the interpretation of Cont Consulting specialists. It does not replace the legal provisions in force.
Sources: Romanian Fiscal Code (Law no. 227/2015), art. 25(3)(l) and (m), art. 28(14), art. 68(7)(k), art. 291(1), art. 298; Methodological Norms approved by Government Decision no. 1/2016, Title II point 16 and Title VII point 68; Catalogue of the classification and useful lives of fixed assets, approved by Government Decision no. 2,139/2004 – as in force on 27.10.2026.