
Updated on 27 October 2026.
In Romania, a vehicle logbook (foaie de parcurs) is required when a company deducts in full the VAT and the costs of a vehicle of up to 3,500 kg and up to 9 seats, including the driver’s seat. If you apply the 50% limitation, you do not have to prove the vehicle’s use with a logbook. A free logbook template is available at the end of this article.
50% deduction or full deduction
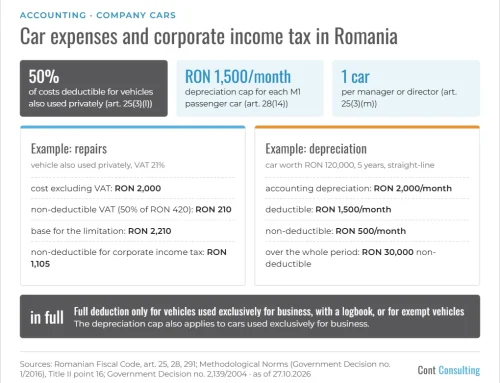
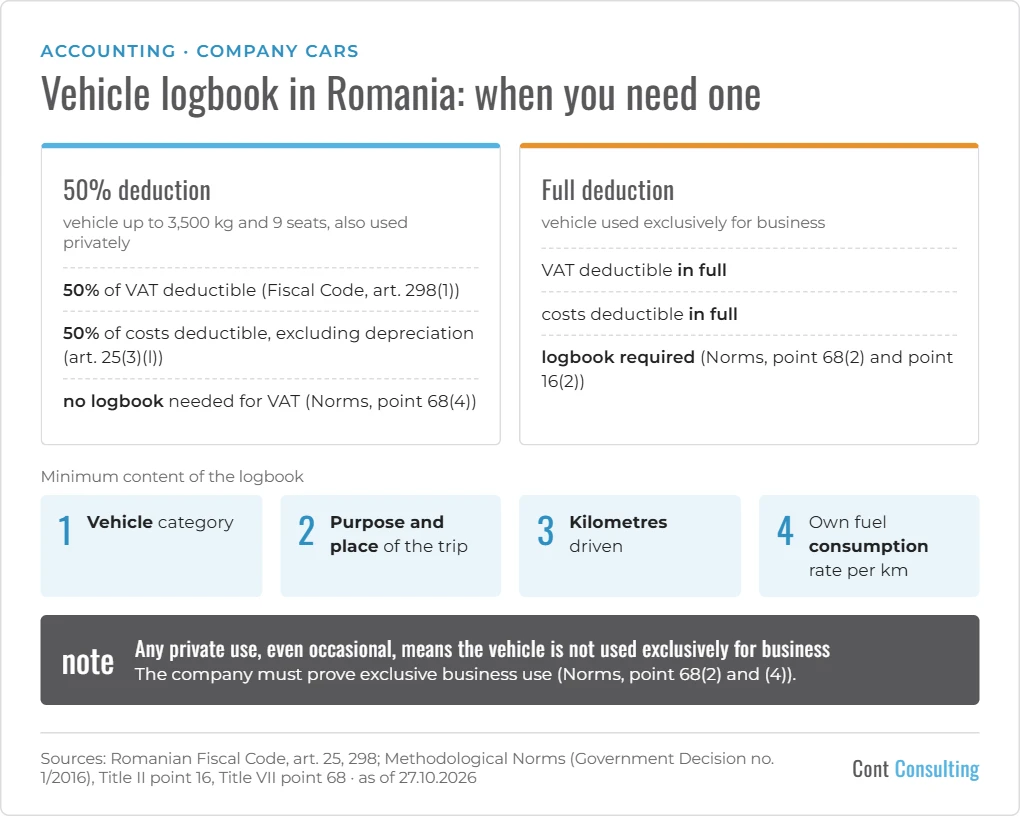
The Romanian Fiscal Code limits to 50% the deduction of VAT (art. 298(1)) and of costs for corporate income tax purposes (art. 25(3)(l)) for vehicles that are not used exclusively for business.
| Situation | VAT | Corporate income tax | Logbook |
|---|---|---|---|
| The vehicle is also used privately | 50% deductible | 50% of costs deductible (depreciation is not included in this limit) | not needed for VAT (Norms, point 68(4)) |
| The vehicle is used exclusively for business | fully deductible | costs fully deductible | required (Norms, point 68(2) and point 16(2)) |
Note: any private use, even occasional, means the vehicle is no longer used exclusively for business (point 68(4)). The company must prove exclusive business use (point 68(2)).
What “exclusively for business” means
The Norms give these examples, among others (point 68(2)): trips in Romania or abroad to customers and suppliers, for market research, to branches, to the bank, to customs, to the post office, to the tax authorities, use by management staff in the course of their duties, and trips for call-outs, servicing and repairs.
Transporting employees to and from work counts as business use only where there are obvious difficulties in using other suitable means of transport (for example, no public transport or a timetable that does not match working hours); otherwise it is private use (point 68(3) and (4)).
Vehicles exempt from the limitation
The deduction is full, even if the vehicle is not used exclusively for business, for: vehicles used exclusively for emergency, security and courier services; vehicles used by sales and purchasing agents; paid passenger transport, including taxis; paid services, including driving schools; rental or leasing (for corporate income tax, only rental to other persons); and vehicles held as goods for sale (Fiscal Code, art. 298(3) and art. 25(3)(l) points 1–5). For sales and purchasing agents, full VAT deduction applies to no more than one vehicle per agent (point 68(6)).
For emergency, security and courier vehicles, the logbook is one of the ways to prove their use (point 68(7)). Our recommendation: keep a logbook for the other exempt vehicles as well, because for corporate income tax the Norms require a logbook for any full deduction (point 16(2)).
What the logbook must contain
At least (point 68(2) and point 16(2)):
- the category of vehicle used;
- the purpose and place of the trip;
- the kilometres driven;
- the company’s own fuel consumption rate per kilometre.
The Norms set only the minimum content, not a specific form. We recommend also recording the date, the registration number, the driver’s name, the odometer readings at departure and arrival, and a signature.
Which costs fall under the 50% limitation
- For VAT: costs directly attributable to the vehicle, such as repairs, maintenance, lubricants, spare parts and fuel (point 68(1)).
- For corporate income tax: also local taxes, compulsory motor insurance (RCA), roadworthiness tests (ITP), the road toll (rovinietă), rent, non-deductible VAT, interest and fees (point 16(3)). Depreciation is not included in this limit (art. 25(3)(l)).
- For managers and directors, the limitation applies to one passenger car per person (art. 25(3)(m)).
For worked examples and the depreciation cap for passenger cars, see our article Car expenses in Romania: what is deductible for corporate income tax.
Micro-enterprises and sole traders (PFA)
- Micro-enterprises pay micro-enterprise income tax rather than corporate income tax, so the corporate income tax limitation does not apply to them. If they are VAT-registered, the VAT rule applies in the same way (art. 298).
- Sole traders (PFA) and other self-employed persons taxed on actual income: the same 50% limitation applies to car costs (Fiscal Code, art. 68(7)(k)). For a full deduction when calculating annual net income, the Norms also require a logbook with the same minimum content (Norms, Title IV point 7(7)).
Vehicle logbook template
We have prepared an Excel template that includes the minimum content required by the Norms, plus the date, the registration number, totals and the closing odometer reading, calculated automatically: download the vehicle logbook template (.xlsx). Enter the consumption rate in litres per kilometre (for example 0.07 for 7 l/100 km).
Our recommendations
- Decide for each vehicle whether you use it exclusively for business or apply the 50% limitation.
- For a full deduction, fill in the logbook for each trip, not at the end of the month.
- Set the own fuel consumption rate for each vehicle in writing.
We can help you record car costs correctly: see our accounting services.
Note: This text is valid on the date of its update, is for information only and reflects the interpretation of Cont Consulting specialists. It does not replace the legal provisions in force.
Sources: Romanian Fiscal Code (Law no. 227/2015), art. 25(3)(l) and (m), art. 68(7)(k), art. 298; Methodological Norms for the application of the Fiscal Code, approved by Government Decision no. 1/2016, Title II point 16, Title IV point 7(7) and Title VII point 68 – as in force on 27.10.2026.