
Updated on 27 October 2026.
When you hire a foreign national in Romania, the tax obligations are the same as for a Romanian employee: you withhold income tax and contributions and declare them every month. The differences concern employment law, the contract and the employee’s tax identification, since at first the employee has no Romanian personal numeric code (CNP).
Who needs a work authorisation
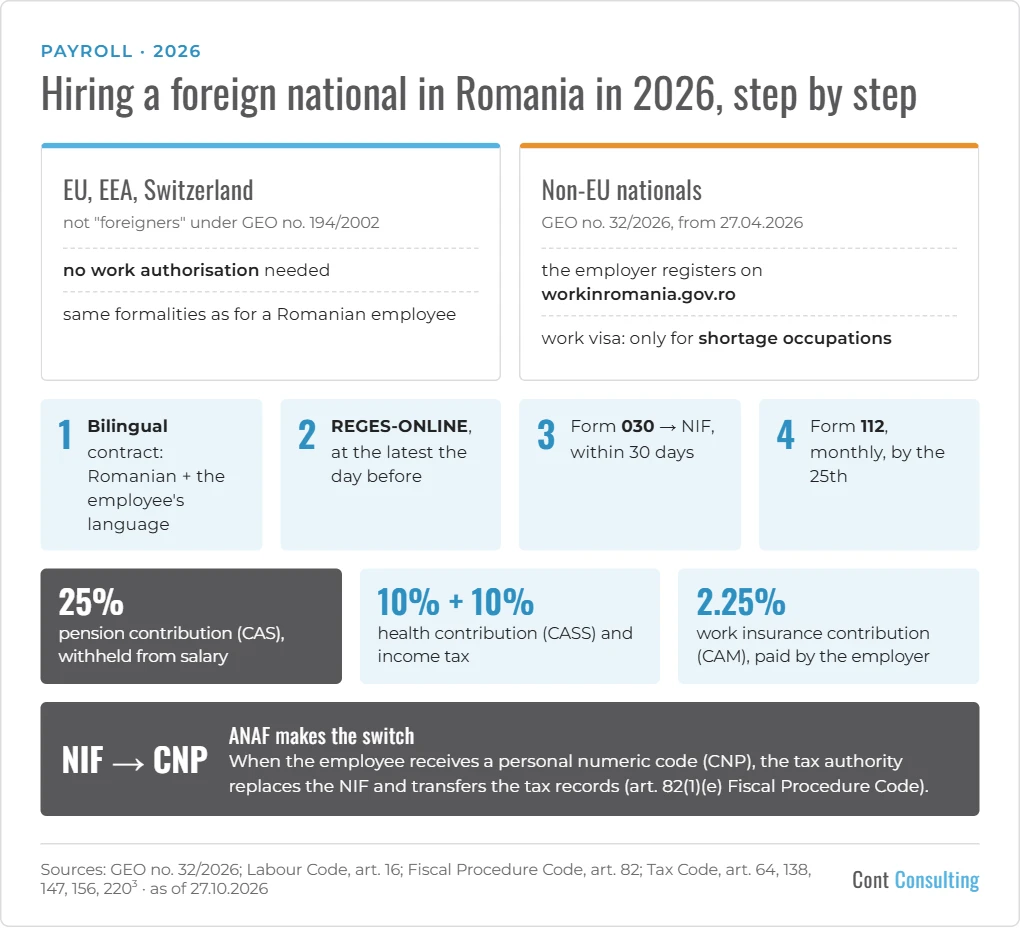
- Citizens of the EU, the European Economic Area and Switzerland are not “foreigners” under the law on the status of foreigners (Government Emergency Ordinance (GEO) no. 194/2002, art. 2(a)). The rules on employing foreigners do not apply to them.
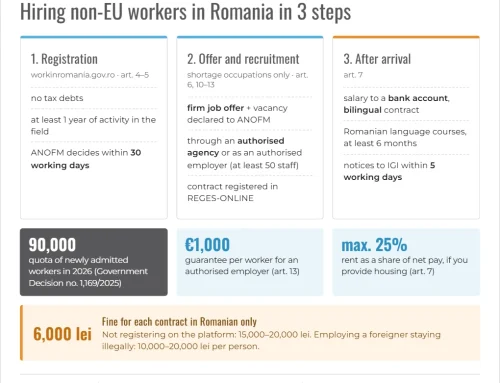
- Nationals of other countries: since 27 April 2026, their access to the labour market is governed by GEO no. 32/2026. The employer registers on the workinromania.gov.ro platform and is entered in the Register of Employers of Foreigners (art. 2(2)(c) and art. 3). Employment on a long-stay work visa is possible only for occupations on the list of shortage occupations (art. 1(3)). These steps are completed before the employee arrives. The employer’s steps are set out in our article on hiring non-EU workers under GEO no. 32/2026.
The employment contract
- The contract is made in writing, in Romanian, no later than the day before work starts (Labour Code, art. 16(1)).
- For a foreign employee, the contract is also made in the language of the employee’s country of origin or in an international language the employee understands (art. 16(19), in force since 27.04.2026).
- Before work starts, the contract is registered in REGES-ONLINE, no later than the day before (art. 16(2); Government Decision no. 295/2025).
The NIF: tax identification without a CNP
- An employee without a CNP receives a tax identification number (NIF) from ANAF (Fiscal Procedure Code, art. 82(1)(e)).
- The application is made on form 030, the tax registration form for individuals without a CNP (ANAF Order no. 1,699/2021), with copies of supporting documents (art. 82(10)): usually the passport or identity document and the employment contract.
- Deadline: 30 days from the first income (art. 82(6)(d) and (e)). In practice, the NIF must be in place before the first form 112 for that employee is filed.
- When the employee receives a CNP, ANAF replaces the NIF with the CNP and transfers the tax records held under the NIF; documents issued earlier remain valid (art. 82(1)(e)).
Contributions, income tax and form 112
| Rate | Legal basis (Tax Code) | |
|---|---|---|
| Social security (pension) contribution (CAS), withheld from salary | 25% | art. 138(a) |
| Health insurance contribution (CASS), withheld from salary | 10% | art. 156 |
| Income tax | 10% | art. 64(1)(b) |
| Work insurance contribution (CAM), paid by the employer | 2.25% | art. 2203(1) |
The employer files form 112 every month, by the 25th of the following month (art. 147(1)), showing the foreign employee under the NIF or, later, the CNP.
What we recommend
- For non-EU employees, start the steps on workinromania.gov.ro early and check that the occupation is on the shortage list.
- Prepare the contract in two languages and register it in REGES-ONLINE no later than the day before work starts.
- File form 030 right after hiring, so that the NIF is ready for the first form 112.
- When the employee receives a CNP, update REGES-ONLINE and your payroll software and check in the ANAF online portal (SPV) that payments have moved to the CNP.
We can help with hiring and payroll: see our payroll and HR services.
Note: This text is valid on the date of its update, is for information only and reflects the interpretation of Cont Consulting specialists. It does not replace the legal provisions in force.
Sources: GEO no. 32/2026, art. 1–3; GEO no. 194/2002, art. 2(a); Labour Code, art. 16; Government Decision no. 295/2025; Fiscal Procedure Code (Law no. 207/2015), art. 82; ANAF Order no. 1,699/2021; Tax Code, art. 64, 138, 147, 156, 2203 – as in force on 27.10.2026.