
Updated on 27 October 2026.
When you sell goods at a distance or supply certain services to private customers in other EU countries, VAT is generally due in the customer’s country. To avoid registering for VAT in each of those countries, you can use OSS (One-Stop Shop): you register once in Romania, file one return and make one payment. OSS is optional: the Romanian Tax Code says the special scheme “may be used” (art. 315(2)).
When VAT is due in the customer’s country
For supplies to non-taxable persons (mainly private individuals) in other EU countries, two rules move the place of supply to the customer’s country:
- intra-Community distance sales of goods: the place of supply is where transport to the customer ends (art. 275(2));
- telecommunications, radio and television broadcasting and electronically supplied services: the place of supply is where the customer is established or lives (art. 278(5)(h)).
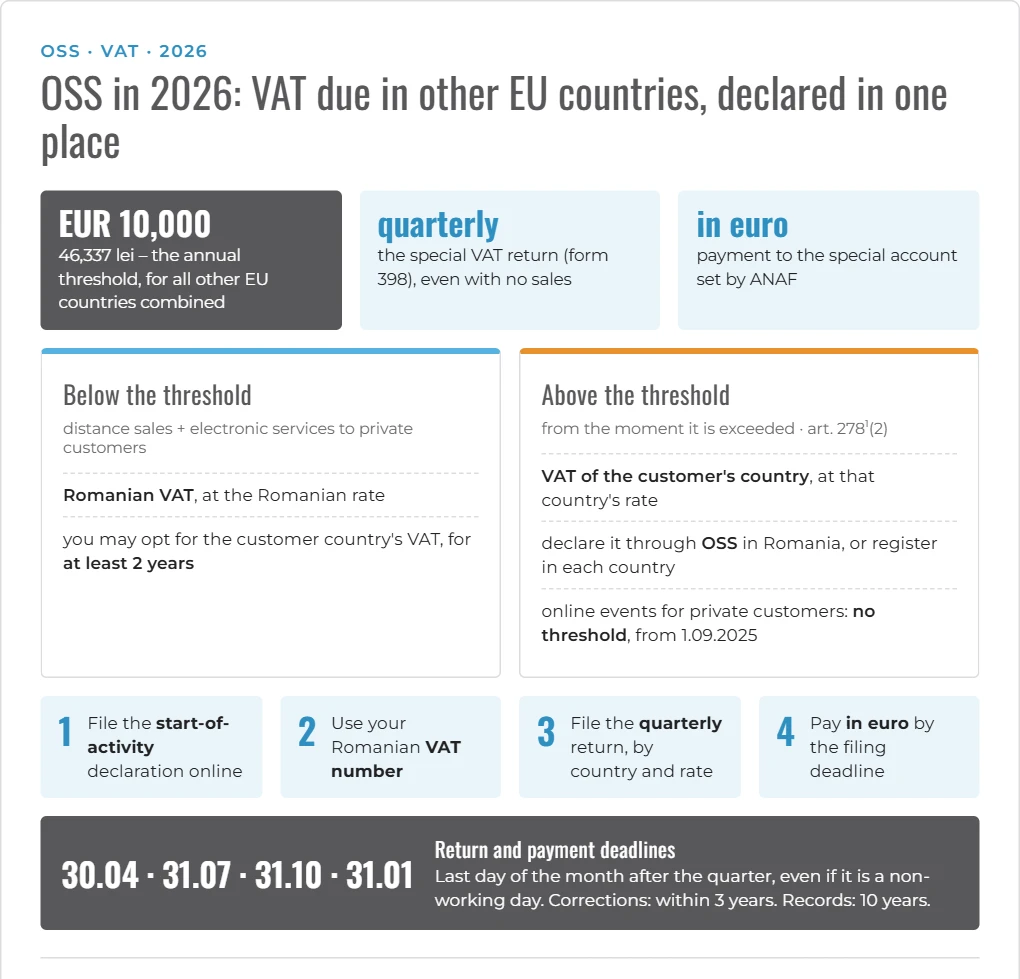
The EUR 10,000 threshold. These two rules do not apply if you are established in a single EU country and the total value, excluding VAT, of these supplies to all other EU countries does not exceed EUR 10,000 (46,337 lei) in the current or the previous year (art. 2781(1) and (5)). Below the threshold you charge Romanian VAT. From the moment the threshold is exceeded, the supplies are taxed in the customer’s country (para. (2)). You may opt to apply the customer-country rule from the start; the option applies for at least two calendar years (para. (3)).
Note: the threshold does not apply to other services to private customers that are taxed in the customer’s country. For example, since 1 September 2025, courses, conferences and events streamed online to private customers are taxed in the customer’s country (art. 278(5)(i), introduced by Government Ordinance no. 22/2025). You can also use OSS for these (art. 315(2)(c)).
The three OSS schemes
| Scheme | Who can use it | What is declared | Number | Return |
|---|---|---|---|---|
| Union (art. 315) | businesses with their place of business or a fixed establishment in Romania | intra-Community distance sales, services to non-taxable persons in countries where you are not established, certain supplies through electronic interfaces | your Romanian VAT number (para. (4)) | quarterly (form 398) |
| Non-Union (art. 314) | businesses with no place of business or fixed establishment in the EU | services to non-taxable persons in the EU | special VAT number (para. (4)) | special VAT return |
| Import (art. 3152) | sellers of goods imported from outside the EU, in consignments of up to EUR 150, excluding excise goods | these distance sales | special number (para. (11)–(13)) | monthly (para. (18)) |
Most Romanian businesses use the Union scheme, which is described below.
The Union scheme step by step (art. 315)
- Registration. File the start-of-activity declaration for the special scheme online (para. (3)). You do not receive a separate “OSS number”: you use your Romanian VAT number, allocated under art. 316 or art. 317 (para. (4)).
- All supplies. The scheme applies to all supplies listed in para. (2), in every country where you do not use the small business exemption under art. 3101 (para. (21)).
- VAT rate. Charge the rate of the customer’s country. In the return, amounts are broken down by country and by rate (para. (7)).
- The return. File the special VAT return (form 398) online for each quarter, by the last day of the following month, even if that is a non-working day and even if you had no supplies in the quarter (para. (6) and (61)). The return is made out in euro, at the ECB exchange rate on the last day of the quarter (para. (12)).
- Payment. Pay the VAT in euro, into the special account indicated by ANAF, by the filing deadline (para. (13)).
- Corrections. Errors are corrected in a later return, within three years of the deadline of the original return (para. (11)).
- Records. Keep records of the supplies under the scheme, make them available electronically on request and keep them for 10 years from the end of the year in which the supplies were made (para. (15)).
- Exclusion. ANAF excludes you from the scheme if you no longer make such supplies, no longer meet the conditions or repeatedly break the rules (para. (5)).
What we recommend
- Track your distance sales and electronic services to private customers in other EU countries every month: the EUR 10,000 threshold is calculated for all countries combined.
- Check whether the customer has a valid VAT number (VIES). Different rules apply to business customers, not OSS.
- Keep evidence of the customer’s country: delivery address, transport documents, payment details.
- Set the VAT rates of the countries you sell to in your invoicing software and check them whenever they change.
- Note the return and payment deadlines: 30 April, 31 July, 31 October and 31 January.
We can help you register for OSS and file the quarterly returns: see our accounting services.
Note: This text is valid on the date of its update, is for information only and reflects the interpretation of Cont Consulting specialists. It does not replace the legal provisions in force.
Sources: Romanian Tax Code (Law no. 227/2015), art. 275, 278, 2781, 3101, 314, 315 and 3152, as in force on 27.10.2026; Government Ordinance no. 22/2025; Law no. 33/2024; ANAF – form 398 (special VAT return, Union scheme).