
Updated on 25 October 2026.
At what price should the sale be made?
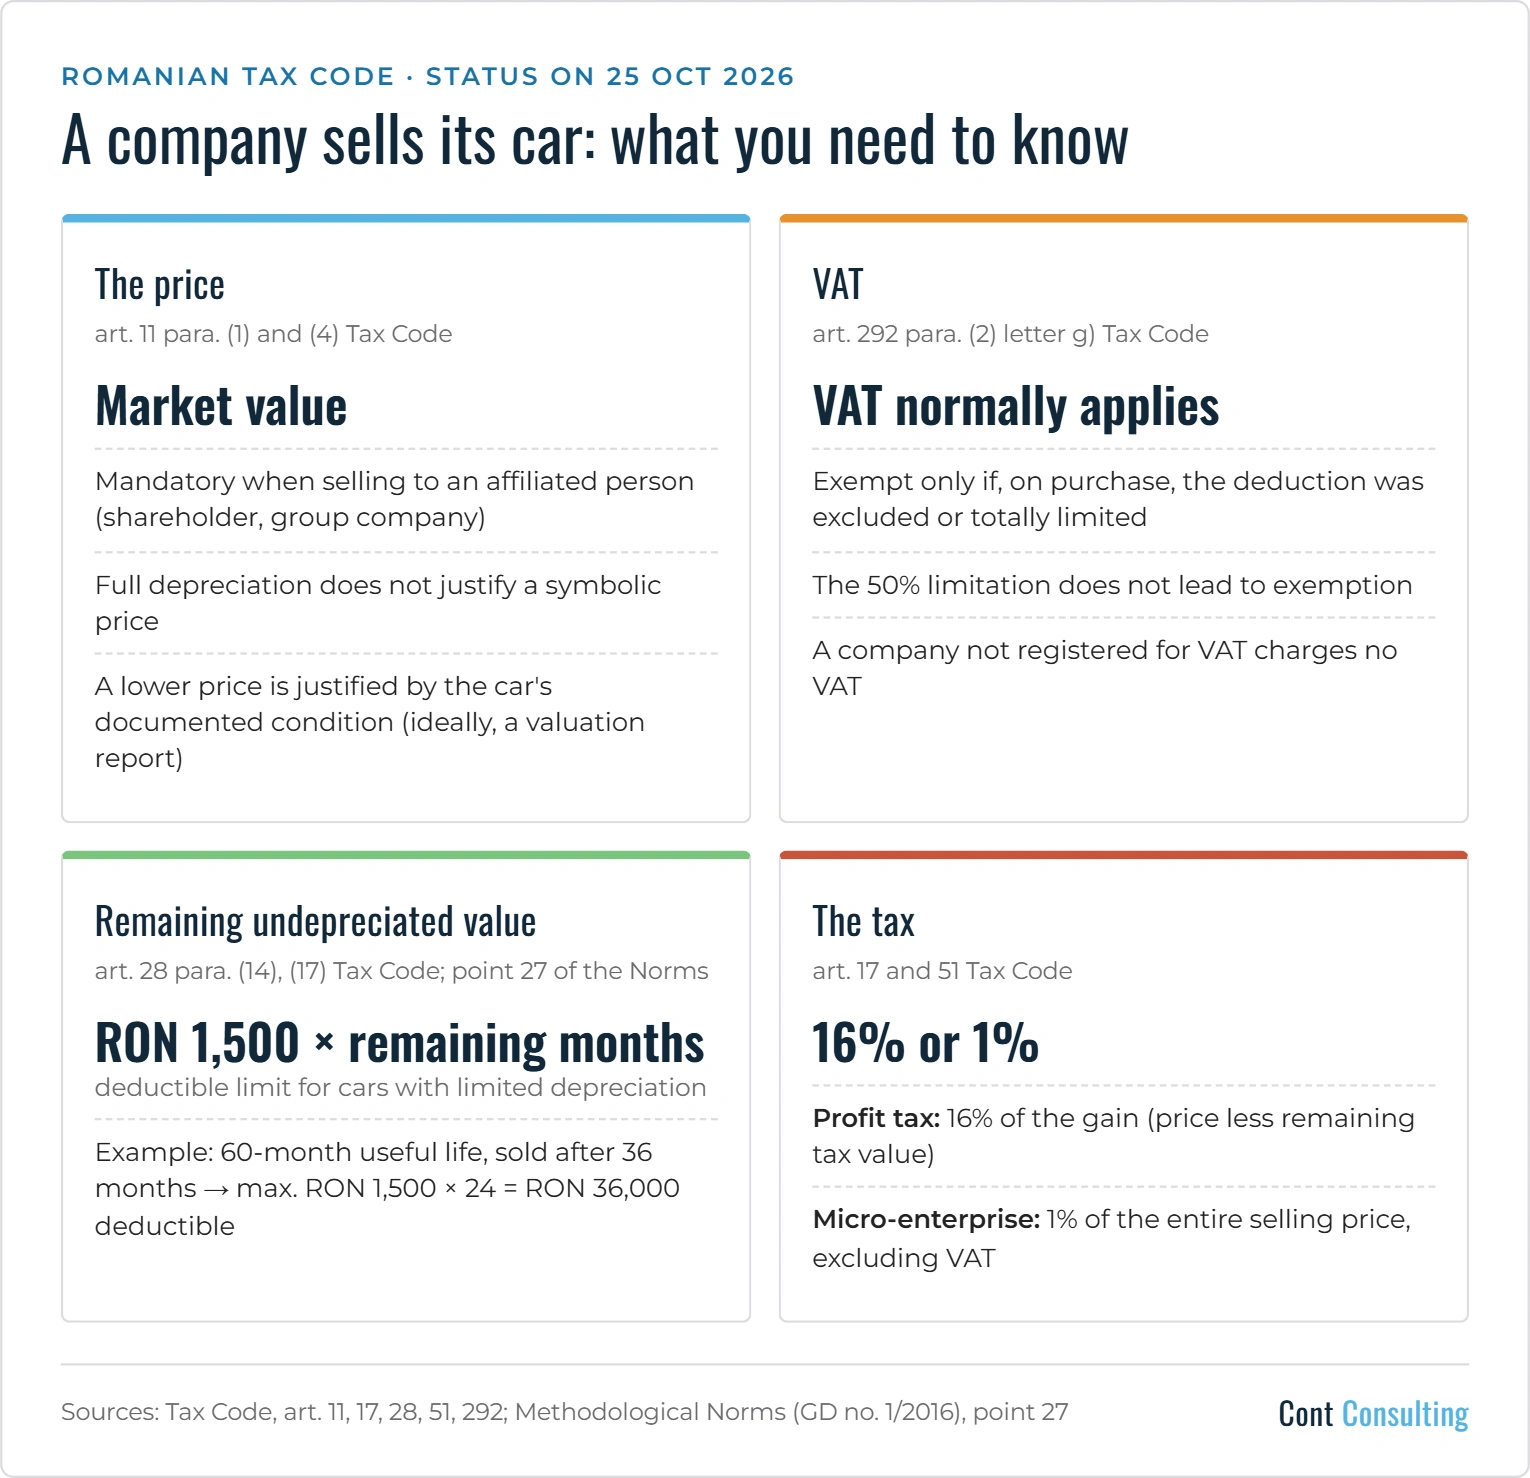
When the vehicle is sold to a person affiliated with the company – for example a shareholder or another company in the same group – the price must comply with the arm’s length principle, and the tax authorities may adjust it if it does not (art. 11 para. (4) of the Romanian Tax Code). In transactions with third parties as well, the tax authorities may disregard a transaction that has no economic purpose or recharacterise it according to its economic substance (art. 11 para. (1)). We therefore recommend that the price be close to market value and that you can justify how it was set, regardless of whether the vehicle is fully depreciated or not.
If the company is registered for VAT purposes, VAT is, as a rule, added to the selling price (see below).
If it is fully depreciated, can it be sold for a “symbolic price”?
This is not recommended. Full depreciation does not mean that the vehicle no longer has a market value. A sale at a symbolic price, especially to an affiliated person, may be adjusted by the tax authorities to market value.
If the vehicle is damaged or defective, can it be sold at a lower value?
Yes, if its condition justifies the lower price and this is documented (inspection reports, repair estimates, photographs). The safest option is a valuation report prepared by an authorised valuer.
Under what conditions can it be sold without VAT?
For a VAT-registered company, the sale of the vehicle is, as a rule, a taxable supply. The exception: the supply is exempt if, on acquisition, the right to deduct VAT was excluded under art. 297 para. (7) letter b) or totally limited under art. 298 (art. 292 para. (2) letter g) of the Tax Code). The 50% limitation of the deduction for passenger cars is not a total limitation, so it does not lead to the exemption.
A company that is not registered for VAT does not charge VAT on the sale.
What is the second-hand regime?
It is a special VAT scheme (art. 312 of the Tax Code) applied by the taxable dealer – the taxable person who, in the course of its business, buys second-hand goods for resale (for example, a used-car dealer). VAT is calculated on the profit margin, i.e. on the difference between the selling price and the purchase price. A company selling its own vehicle, used in its business, does not apply this scheme.
Switching from VAT-registered to non-registered
A company that deducted VAT on the purchase of the vehicle and cancels its VAT registration before 5 years have passed since the purchase must adjust the VAT initially deducted, in proportion to the remaining period (art. 305 of the Tax Code – adjustment for capital goods).
Is the remaining undepreciated value deductible on sale?
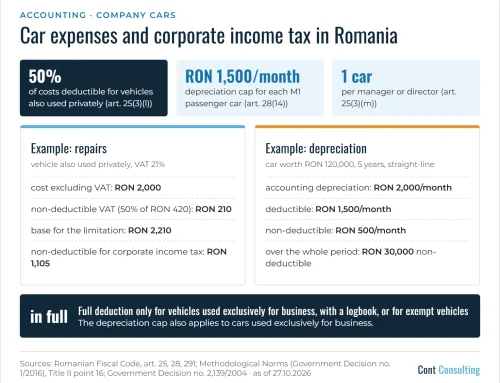
The general rule is that the gain or loss on the sale of a fixed asset is calculated based on its tax value less tax depreciation (art. 28 para. (17) of the Tax Code). The Code, however, makes an exception for passenger cars whose depreciation is deductible up to RON 1,500 per month (M1 category vehicles with no more than 9 seats, referred to in art. 28 para. (14)).
For these cars, the Methodological Norms for the application of the Tax Code state that, upon derecognition, “the remaining undepreciated value is deductible up to RON 1,500 multiplied by the number of months remaining to be depreciated from the normal useful life established by the taxpayer according to the Catalogue on the classification and normal useful lives of fixed assets” (point 27 of the Methodological Norms, Title II, approved by Government Decision no. 1/2016).
Example: a car with a normal useful life of 60 months is sold after 36 months. At most RON 1,500 × 24 months = RON 36,000 of the remaining undepreciated value is deductible.
The limit does not apply to the vehicles exempted under art. 28 para. (14): those used exclusively for emergency, security and protection or courier services, by sales and purchasing agents, for test drives and demonstrations, for paid passenger transport or for paid services (rental, operating leasing, driving schools).
Is tax payable on the sale of the vehicle?
Yes, depending on the company’s tax regime:
- Profit tax payer: the gain (selling price less the remaining undepreciated tax value, excluding VAT) is included in taxable profit, taxed at 16% (art. 17 of the Tax Code).
- Micro-enterprise: the 1% rate applies to the entire selling price, excluding VAT (art. 51 para. (1) of the Tax Code, single rate from 1 January 2026).
Note: This text is valid as of the date of its update, is for guidance only and represents an interpretation by the specialists of Cont Consulting, and is not intended to replace the legal provisions in force. We are not liable for any damages arising from the use of this material for legal purposes or as evidence in any potential litigation. The amounts and figures used in the article above were those in force at the time of the update and may be subject to change.