
Updated on 27 October 2026.
The Romanian Tax Code sets two local taxes on advertising: the tax on advertising services (art. 477) and the tax on billboards and other advertising displays (art. 478). Both are paid to the local budget, and the exact amount is set by the local council.
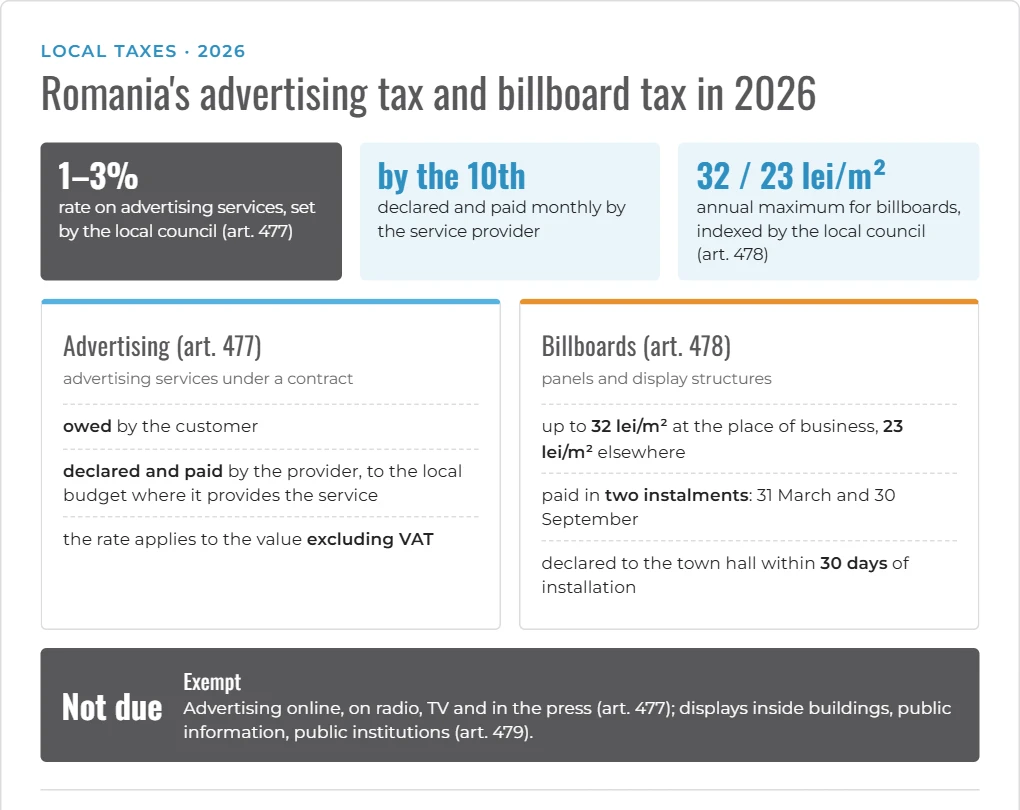
Tax on advertising services (art. 477)
- Who owes it: anyone who receives advertising services in Romania under a contract or other arrangement (para. (1)).
- What is excluded: advertising through print and audiovisual mass media, meaning newspapers and other printed matter, radio, television and the internet (para. (1) and (2)).
- Where it is paid: to the local budget of the place where the provider supplies the services (para. (3)).
- How much: the rate set by the local council, between 1% and 3%, applied to the value of the services excluding VAT (para. (4)–(6)).
- Who declares and pays it: the service provider, monthly, by the 10th of the month after the one in which the contract came into force (para. (7)).
Example. An advertising contract of 10,000 lei excluding VAT, in a town where the local council has set a 3% rate: the tax is 300 lei, declared and paid by the provider.
Tax on advertising displays (art. 478)
- Who owes it: anyone who uses a panel, display or display structure for advertising, other than in the cases covered by art. 477; it is paid to the budget of the town where the panel is located (para. (1)).
- How much: yearly, per square metre or fraction, the amount set by the local council: up to 32 lei/m² for displays at your place of business and up to 23 lei/m² for any other panel (para. (2)). The amounts are indexed every year by the local council (art. 491). The tax is recalculated for the months in which you advertise (para. (3)).
- Payment: yearly, in two equal instalments, by 31 March and 30 September; a tax of up to 50 lei is paid in full by 31 March (para. (4)).
- Declaration: to the town hall, within 30 days of installing the panel (para. (5)).
When the taxes are not due (art. 479)
- public institutions, except when they advertise economic activities (para. (1));
- a person who rents out a panel to someone else does not pay the display tax; in this case, the person renting the panel pays the art. 477 tax (para. (2));
- posters and panels inside buildings (para. (3));
- identification panels for energy installations, warning and traffic signs, and other public-interest and educational information (para. (4));
- displays on vehicles that are not built for advertising (para. (5)).
What we recommend
- Check the local council’s decision for 2026: the advertising tax rate and the amounts per m² for displays.
- If you provide advertising services, declare and pay the tax monthly, by the 10th, and state in the contract that you re-invoice it.
- For your own business or shop, declare the panel within 30 days of installation and pay the tax by 31 March and 30 September.
- Advertising online, on radio, on TV and in the press is not subject to art. 477.
We can help you declare local taxes: see our accounting services.
Note: This text is valid on the date of its update, is for information only and reflects the interpretation of Cont Consulting specialists. It does not replace the legal provisions in force.
Sources: Romanian Tax Code (Law no. 227/2015), art. 477, 478, 479 and 491, as in force on 27.10.2026; Law no. 112/2016; Government Emergency Ordinance no. 78/2025.