
Updated on 27 October 2026.
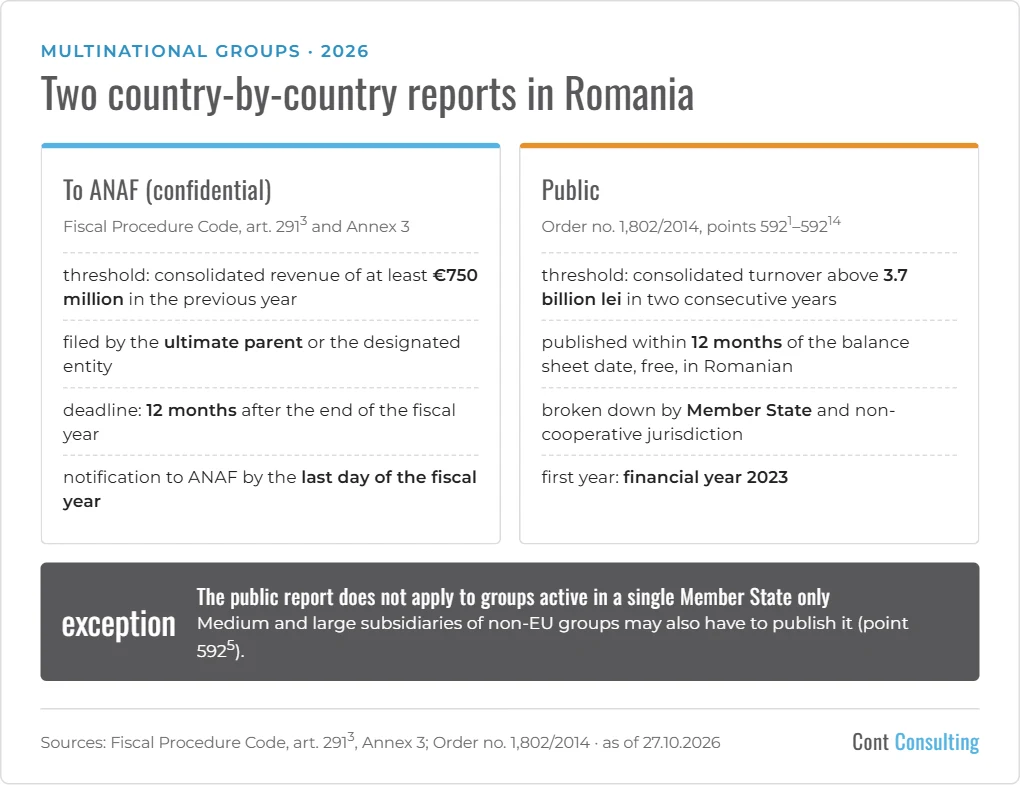
Large multinational groups have two country-by-country reporting obligations in Romania: a confidential report filed with the tax authority (ANAF) and exchanged between tax authorities, and, since 2023, a public income tax information report.
1. The country-by-country report filed with ANAF
- Who: multinational groups with consolidated revenue of at least €750 million in the previous year. Groups below this threshold are excluded (Fiscal Procedure Code, Annex 3, section I point 4).
- Who files: the ultimate parent entity resident in Romania or another designated reporting entity (art. 2913(1)). If the parent is outside the EU, in certain situations a group entity resident in Romania files the report.
- Content: for each jurisdiction, revenue, profit or loss before tax, tax paid and accrued, stated capital, accumulated earnings, number of employees and tangible assets, plus the list of group entities and their main activities (art. 2913(3)).
- Deadline: 12 months after the last day of the group’s fiscal year (art. 2913(1)). ANAF passes the report to the other Member States within 15 months (para. (4)).
- Notification: each group entity resident in Romania tells ANAF whether it files the report or who files it and where, by the last day of the reporting fiscal year, but no later than the deadline for its tax return for the previous year (Annex 3, section II points 7 and 8).
The rules were introduced by Government Emergency Ordinance no. 42/2017, which transposes Directive (EU) 2016/881.
2. The public income tax information report
- Who: ultimate parent companies and standalone undertakings with consolidated net turnover above 3.7 billion lei (about €750 million) in each of the last two financial years. In certain cases, medium and large subsidiaries of non-EU groups must also publish it (Order no. 1,802/2014, points 5923 and 5925).
- When it does not apply: groups active in a single Member State only (point 5924).
- Content: income tax information, broken down by Member State and for the jurisdictions on the EU lists of non-cooperative jurisdictions.
- Deadline: publication within 12 months of the balance sheet date, free of charge, in Romanian. The first reporting year was financial year 2023, with publication by 31 December 2024 (Order no. 2,048/2022, art. III1).
The rules transpose Directive (EU) 2021/2101 and were added to Order no. 1,802/2014 by Order no. 2,048/2022. For entities applying IFRS, equivalent rules are in Order no. 2,844/2016.
What we recommend
- Check every year whether the group exceeds the thresholds, based on the consolidated financial statements.
- Decide early which entity files the report with ANAF and send the notification on time.
- If you are a subsidiary of a large non-EU group, ask the parent company early for the information needed for the public report.
We can help you assess your reporting obligations: see our consultancy services.
Note: This text is valid on the date of its update, is for information only and reflects the interpretation of Cont Consulting specialists. It does not replace the legal provisions in force.
Sources: Romanian Fiscal Procedure Code (Law no. 207/2015), art. 2913 and Annex 3; Order no. 1,802/2014, points 5921–59214, added by Order no. 2,048/2022 – as in force on 27.10.2026.