
Updated on 26 October 2026.
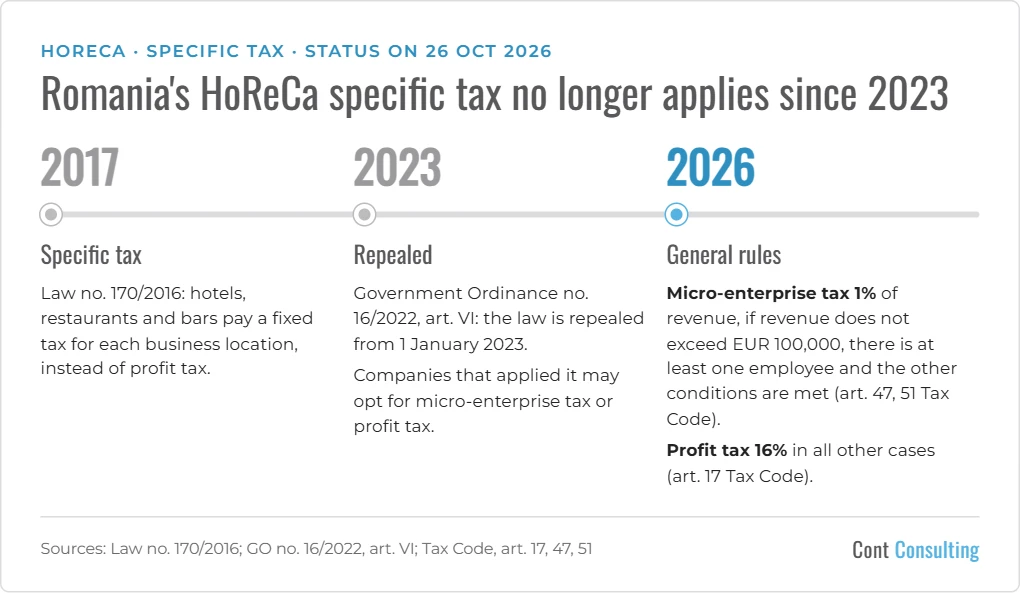
The specific tax no longer applies. Law no. 170/2016 on the specific tax for certain activities was repealed with effect from 1 January 2023, by art. VI para. (1) of Government Ordinance no. 16/2022. The last year for which it was due was 2022.
What the specific tax was
Between 1 January 2017 and 31 December 2022, companies in tourism, hotels, restaurants, bars and catering (NACE Rev. 2 codes 5510, 5520, 5530, 5590, 5610, 5621, 5629 and 5630) paid an annual specific tax instead of profit tax. It was calculated for each business location, based on floor area, the rank of the locality and seasonality, and did not depend on the profit earned.
What happened when it was repealed
From 1 January 2023, companies that had applied the specific tax until 31 December 2022 could opt, by way of exception from the usual conditions, for micro-enterprise income tax or for profit tax (art. VI para. (2) of Government Ordinance no. 16/2022).
What applies in 2026
HoReCa companies no longer have a special tax regime. They pay, as the case may be:
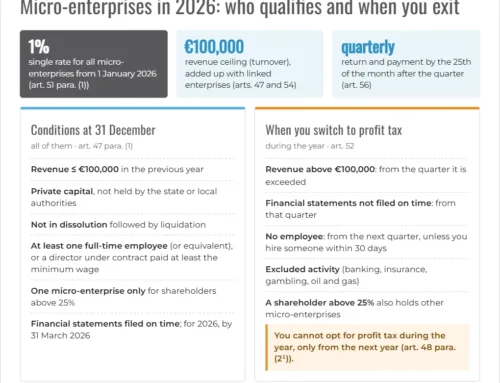
- micro-enterprise income tax of 1% of revenue, if they meet the conditions of art. 47 of the Romanian Tax Code: revenue of no more than EUR 100,000 in the previous year (together with linked enterprises), at least one employee, annual financial statements filed on time and the other conditions laid down by law (art. 47 para. (1) and art. 51 para. (1) of the Tax Code);
- profit tax of 16%, in all other cases (art. 17 of the Tax Code).
We cannot say which regime suits a particular company without analysing its figures. We can help you with this analysis – see Tax and Accounting Consulting.
Note: This text is valid as of the date of its update, is for guidance only and represents an interpretation by the specialists of Cont Consulting, and is not intended to replace the legal provisions in force. We are not liable for any damages arising from the use of this material for legal purposes or as evidence in any potential litigation.