
Updated on 26 October 2026.
A company paying profit tax in Romania can support an association, a foundation, a religious unit or a library at almost no cost of its own, if the sponsorship stays within the Tax Code limits. The amount given is not a deductible expense. It comes directly off the profit tax, and any unused allowance can be redirected from the tax. Below are the rules in force and the changes of recent years.
Sponsorship, patronage, private scholarships
- Sponsorship is the legal act by which two parties agree to transfer goods or money to support non-profit activities of the beneficiary. The contract must be in writing and state the object, value and duration (art. 1 paras. (1) and (2) of Law no. 32/1994).
- Patronage (mecenat) is a gift to an individual, with no consideration, in the cultural, artistic, medical or scientific fields. It requires a notarised deed (art. 1 paras. (3) and (4) of the same law).
- Private scholarships (Law no. 376/2004) no longer qualify for the tax incentive from 1 January 2024. The current wording of art. 25 para. (4) letter i) of the Tax Code covers only sponsorship and patronage.
Eligible beneficiaries include non-profit legal entities active in Romania in the cultural, artistic, educational, scientific, humanitarian, religious, philanthropic, sports, medical, social assistance and environmental fields, among others (art. 4 letter a) of Law no. 32/1994).
How much comes off the profit tax
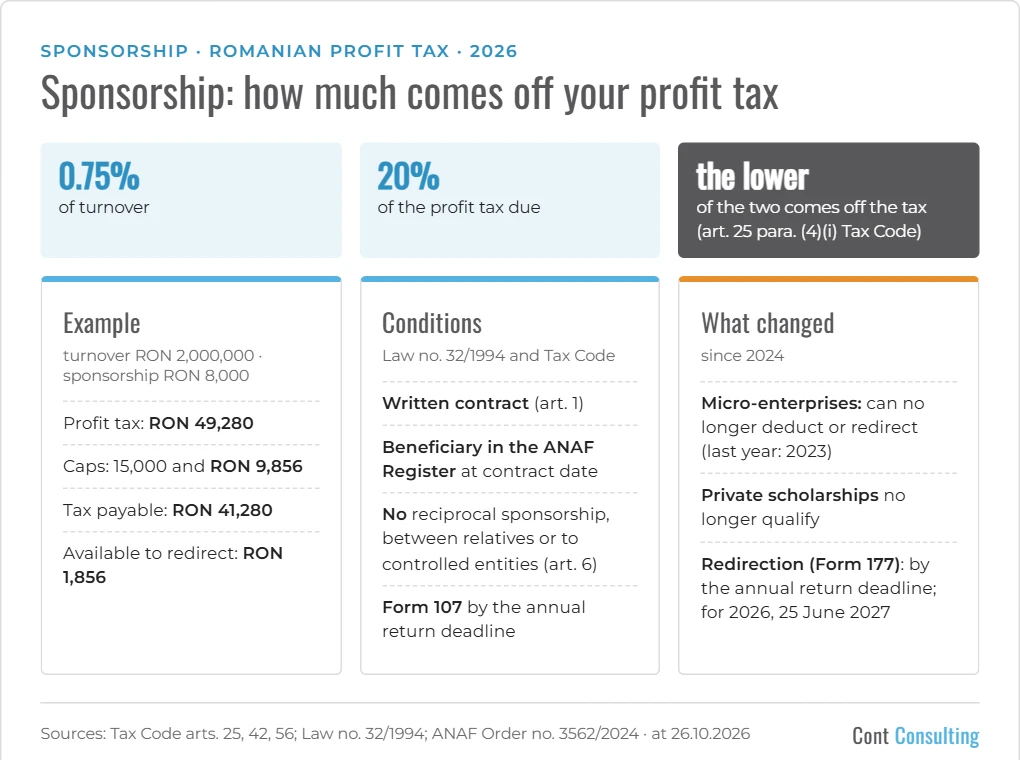
The sponsorship amount is deducted from the profit tax due, up to the lower of two values (art. 25 para. (4) letter i) of the Tax Code):
- 0.75% of turnover;
- 20% of the profit tax due.
If the beneficiary is a non-profit legal entity or a religious unit, the amount can be deducted only if the beneficiary was listed, on the date the contract was signed, in the Register of entities/religious units eligible for tax deductions published on the ANAF website (art. 25 para. (4) letter i) and para. (4^1)).
Example. A company has a turnover of RON 2,000,000 and an accounting profit of RON 300,000, which already includes the RON 8,000 sponsorship. The sponsorship expense is non-deductible (art. 25 para. (4) letter i)), so it is added back: taxable profit is RON 308,000, assuming no other adjustments. Profit tax is 308,000 × 16% = RON 49,280.
| Cap | Calculation | Amount |
|---|---|---|
| 0.75% of turnover | 2,000,000 × 0.75% | RON 15,000 |
| 20% of profit tax | 49,280 × 20% | RON 9,856 |
| The lower cap applies | RON 9,856 |
The company deducts the full RON 8,000 sponsorship and pays tax of 49,280 − 8,000 = RON 41,280. The difference up to the cap, 9,856 − 8,000 = RON 1,856, can be redirected using Form 177. In effect, the sponsorship cost the company nothing, and RON 1,856 of its tax can go to another sponsored entity.
Redirecting profit tax
If the cap was not fully used, the company can ask ANAF to pay the difference, out of its tax, directly to a sponsored entity. The request is made on Form 177 “Request for redirection of profit tax”, by the deadline for the annual profit tax return (art. 42 para. (4) of the Tax Code and ANAF President’s Order no. 3562/2024). The beneficiary must be listed in the Register on the date ANAF makes the payment.
Mind the deadline: the annual return for 2025 was due by 25 March 2026. For 2026, the deadline becomes 25 June 2027 (art. 42 para. (1), as amended by Government Emergency Ordinance no. 8/2026), and the redirection deadline moves with it.
Micro-enterprises
Micro-enterprises can no longer deduct sponsorship from their tax or redirect it. The last tax year in which they could do so was 2023 (art. 56 paras. (2^4) and (2^5) of the Tax Code). A micro-enterprise can still sponsor, but the amount does not reduce its tax. The current micro-enterprise rules are in our article Micro-enterprise income tax in Romania in 2026.
Conditions and obligations
- A written contract stating the object, value and duration; for patronage, a notarised deed (art. 1 of Law no. 32/1994).
- A beneficiary listed in the ANAF Register on the contract date or, for redirection, on the payment date.
- No reciprocal sponsorship, no sponsorship between relatives or in-laws up to the fourth degree, and no sponsorship of an entity the sponsor directly manages or controls (art. 6 of Law no. 32/1994).
- No commercial advertising for the sponsor. Only mentioning its name, brand or image is allowed (art. 5 of Law no. 32/1994).
- The information return on beneficiaries (Form 107), by the annual profit tax return deadline (art. 42 para. (3) of the Tax Code).
We can help with calculating the cap and with Forms 107 and 177: see Tax and accounting consulting.
Note: This text is valid on the date of the update, is for information only and reflects the interpretation of Cont Consulting’s specialists. It does not replace the legal provisions in force.
Sources: Romanian Tax Code (Law no. 227/2015), arts. 25, 42 and 56; Law no. 32/1994, arts. 1, 4, 5 and 6; ANAF President’s Orders no. 3562/2024 and no. 355/2024. Consolidated versions checked on 26.10.2026.